Showing posts with label Finance. Show all posts

Thursday, November 20, 2008

Mad Max and the Meltdown

Daniel Henninger thinks the current financial crisis is linked to the trend of secularism taking over the country:
This year we celebrate the desacralized "holidays" amid what is for many unprecedented economic ruin -- fortunes halved, jobs lost, homes foreclosed. People wonder, What happened? One man's theory: A nation whose people can't say "Merry Christmas" is a nation capable of ruining its own economy.

One had better explain that.

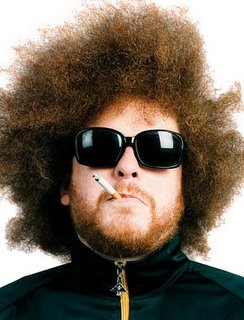
Yes, one better. Click through this post's title for the whole thing - he makes a pretty good case. But the best part of his post may be the caption to this picture:

Mortgage-backed security survivor.

Ain't it the truth?

Wednesday, November 5, 2008

Post-Election Stock Slump

Uh, oh:
The stock market posted its biggest plunge following a presidential election as reports on jobs and service industries stoked concern the economy will worsen even as President-elect Barack Obama tries to stimulate growth.

I've been advising that the stock market will settle down after the election; I still think it will, so this may not necessarily mean anything. Yet. Still, it's ominous that this is the biggest drop following an election. It's not getting much press - and for good reason, considering the other news behind it - but I wonder how the news would be covered if McCain had won.

My advice remains the same: diversify and invest for the long term. Try to ignore the day-to-day news.

Sunday, November 2, 2008

1.95 Gas!

We haven't seen this since we drove to Washington D.C three summers ago.


No guarantee it'll stay this low and, of course, low energy prices isn't necessarily good news for us here in Oklahoma. But, hey, enjoy it while you can. It may not come around again for a long, long time.

Friday, October 17, 2008

Free Markets and Freedom

John Stossel has a column about how markets and freedom:
(G)overnments have regulated and subsidized the housing and financial industries for years. Fannie Mae and Freddie Mac were created to interfere in those markets. Had actual private companies invested in those mortgages, they would have been subject to market checks. But they were not. The results were predictable.

Now we will get a new onslaught of regulation. This intervention will fail and stifle innovation because, as Adam Smith and Friedrich Hayek taught, markets are too complex to manipulate beneficially. Life works best when decisions are bottom up. But pundits have no clue about spontaneous order. Instead, they talk about who will "run America."

This faith in political solutions thrives in the face of repeated government failure. Big farm bills have raised the price of food and squeezed out small farms. Campaign finance reform made it harder to challenge incumbents. FEMA couldn't deliver water to hurricane-ravaged New Orleans as well as Wal-Mart did. Medicare has a $35 trillion unfunded liability over the next 75 years.

Yet the media and political class call for more government control. What puzzles me is why citizens don't act like the skaters we tried to boss around. The skaters wanted freedom. Citizens might desire this too, but the political class assumes they want and need direction.

"It's like we believe that when one man is chosen to be president, suddenly he rises above all the rest of us." says the Cato Institute's David Boaz. "Suddenly politicians can do anything: give us health care, better lives, better jobs. But politicians can't do most of that stuff."

"Fortunately," he adds, "Most of life is outside the government sector." That's the part of life that keeps getting better.

Something to keep in mind when you pull the lever on election day.

Wednesday, October 1, 2008

Financial Crisis Solution

Who knows what the second day after Monday's stock market plunge holds? Yesterday, the market recovered 500 of the 777 points it lost but things are still in flux. Is there a roll for government in all of this.

Perhaps. Dave Ramsey offers a solution that seems sound to me. He tells readers to cut and paste his suggestions in e-mails to their Congressmen so posting it here instead:

Years of bad decisions and stupid mistakes have created an economic nightmare in this country, but $700 billion in new debt is not the answer. As a tax-paying American citizen, I will not support any congressperson who votes to implement such a policy. Instead, I submit the following three steps:

Common Sense Plan.

I. INSURANCE

A. Insure the subprime bonds/mortgages with an underlying FHA-type insurance. Government-insured and backed loans would have an instant market all over the world, creating immediate and needed liquidity.

B. In order for a company to accept the government-backed insurance, they must do two things:

1. Rewrite any mortgage that is more than three months delinquent to a 6% fixed-rate mortgage.
a. Roll all back payments with no late fees or legal costs into the balance. This brings homeowners current and allows them a chance to keep their homes.
b. Cancel all prepayment penalties to encourage refinancing or the sale of the property to pay off the bad loan. In the event of foreclosure or short sale, the borrower will not be held liable for any deficit balance. FHA does this now, and that encourages mortgage companies to go the extra mile while
working with the borrower—again limiting foreclosures and ruined lives.

2. Cancel ALL golden parachutes of EXISTING and FUTURE CEOs and executive team members as long as the company holds these government-insured bonds/mortgages. This keeps underperforming executives from being paid when they don’t do their jobs.

C. This backstop will cost less than $50 billion—a small fraction of the current proposal.


II. MARK TO MARKET

A. Remove mark to market accounting rules for two years on only subprime Tier III bonds/mortgages. This keeps companies from being forced to artificially mark down bonds/mortgages below the value of the underlying mortgages and real estate.

B. This move creates patience in the market and has an immediate stabilizing effect on failing and ailing banks—and it costs the taxpayer nothing.


III. CAPITAL GAINS TAX

A. Remove the capital gains tax completely. Investors will flood the real estate and stock market in search of tax-free profits, creating tremendous—and immediate—liquidity in the markets. Again, this costs the taxpayer nothing.

B. This move will be seen as a lightning rod politically because many will say it is helping the rich. The truth is the rich will benefit, but it will be their money that stimulates the economy. This will enable all Americans to have more stable jobs and retirement investments that go up instead of down. This is not a time for envy, and it’s not a time for politics. It’s time for all of us, as Americans, to
stand up, speak out, and fix this mess.


The "mark-to-market" move is endorsed by the Wall Street Journal as well.

No matter what happens, though, in the long run, this will all sort out. So don't worry.

Friday, September 26, 2008

Keeping it Simple

Related to my post about keeping your investment strategy simple, here's a book review of The Gone Fishin' Portfolio by Alexander Green:
Mr. Green's formula is really an extension of the "non-correlation" approach that David Swenson uses to manage the Yale Endowment Fund and that other followers of modern portfolio theory have developed to achieve substantial returns with less volatility -- putting money into markets that may move in different (non-correlated) directions. The essential trick is to invest beyond U.S. borders and to invest in alternatives to common stocks, like commodities that zig when the stock market zags (gold is an example).

Mr. Green is a big fan of no-load mutual funds like Vanguard's, with their low-cost, tax-minimizing structure. He recommends buying 10 of them. The majority of such funds are heavily invested in the stock markets of the U.S., Europe, Asia and emerging-market countries; but the funds also take smaller positions in bonds (Treasury Inflation-Protected Securities, high-quality and high-yield corporates) and hard assets (gold and real-estate investment trusts). Investing in such a variety of unrelated assets, Mr. Green argues, provides built-in stabilizers to protect your portfolio on the downside when Wall Street stumbles.

Good advice. Keep your investment strategy simple and it'll pay off. Best of all, you'll sleep at night.